The Deceptively Simple Choice
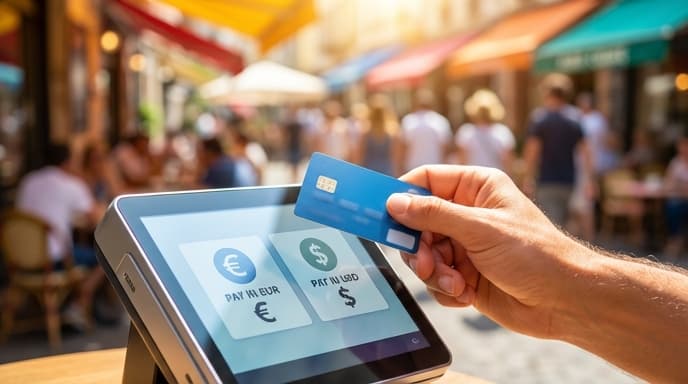
You're at a restaurant in Paris, and the bill is €50. You hand over your US credit card, and the waiter brings a terminal that asks, 'Would you like to pay in EUR or USD?' Seeing the price in familiar dollars might seem easier, but selecting that option is a common travel mistake that can add unnecessary costs to your trip. This 'service' is called Dynamic Currency Conversion (DCC).
What Is Dynamic Currency Conversion (DCC)?
DCC is a financial service offered by foreign merchants and ATM operators that converts the cost of your purchase into your home currency at the point of sale. On the surface, it provides clarity by showing you exactly what you'll be charged in a currency you understand. However, this convenience comes at a hidden cost.
Why It's a Bad Deal
When you choose to pay in your home currency via DCC, you are opting out of the competitive exchange rate offered by your own bank or credit card network (like Visa or Mastercard). Instead, you are accepting an exchange rate set by the merchant's bank or a third-party processor. This rate is almost always significantly worse than the market rate and typically includes extra service fees.
- Poor Exchange Rates: The DCC rate can be several percentage points worse than the rate your own bank would give you.
- Hidden Fees: The final price in your home currency often has a markup or commission baked into it, which isn't always transparent.
- You Still Might Pay a Fee: Even if you pay via DCC, your home bank might still charge you a foreign transaction fee, meaning you get hit with double charges.
Essentially, the merchant gets a small commission for getting you to use DCC, and you end up paying more for the exact same item.
The Golden Rule: Always Choose Local
The rule is simple and should be followed every time you use a card abroad, whether at a store, hotel, or ATM:
Always, without exception, choose to pay in the local currency.
When you select the local currency (Euros in Europe, Yen in Japan, etc.), the transaction is sent to your credit card network (Visa/Mastercard) for conversion. These networks offer some of the best, most competitive exchange rates available. Even if your card has a foreign transaction fee (typically around 3%), the total cost will almost always be lower than using DCC.
Frequently Asked Questions (FAQ)
What if the cashier chooses my home currency for me?
This can happen. Always check the receipt before you sign or enter your PIN. If you see it has been converted to your home currency without your permission, ask them to cancel the transaction and run it again in the local currency.
Does this apply to ATMs too?
Yes. Foreign ATMs will often offer to convert the withdrawal amount to your home currency. Just like at a merchant, you should decline this offer and choose to proceed 'without conversion' in the local currency.
Is DCC the same as a foreign transaction fee?
No. A foreign transaction fee is charged by your own bank for processing a transaction in a different country. DCC is a separate service offered by the foreign merchant's bank. To be a savvy traveler, use a credit card that has no foreign transaction fees and always decline DCC.
Key Takeaways
- Dynamic Currency Conversion (DCC) is an option to pay in your home currency when traveling abroad.
- You should always decline DCC and choose to pay in the local currency.
- DCC uses uncompetitive exchange rates and may include hidden fees, making your purchase more expensive.
- Your own bank or credit card network (Visa/Mastercard) will give you a much better exchange rate.
- This rule applies to both purchases at stores and withdrawals from ATMs.